Cruise Travel Insurance: What It Covers and What Matters
Cruise travel insurance can protect more than the price of your cabin, but only when the loss fits the policy. The smart move is to compare cancellation, travel medical, evacuation, delay, and baggage benefits separately instead of trusting the plan name.
My quick take: protect the costs you could not comfortably lose, then give medical evacuation extra attention on remote itineraries. The certificate of insurance controls every claim, so treat benefit summaries as shopping labels rather than promises.
What cruise travel insurance can cover
A comprehensive plan bundles several kinds of protection, and each has its own limit, trigger, exclusions, and documentation rules. The CDC separates travel disruption, travel health, and medical evacuation coverage because one benefit does not automatically replace another.
- Trip cancellation: may reimburse eligible prepaid, nonrefundable costs when you cancel before departure for a reason specifically listed in the policy.
- Trip interruption: may reimburse eligible unused trip costs and added transportation when a covered event cuts the trip short.
- Travel medical: may reimburse covered care for an illness or injury during the trip, subject to deductibles, exclusions, and plan limits.
- Emergency evacuation and repatriation: may pay for approved transport to an appropriate medical facility and, when the terms allow, transport home or return of remains.
- Travel delay and missed connection: may reimburse eligible meals, lodging, and transportation after the stated delay threshold or a covered missed departure.
- Baggage: may cover eligible loss, damage, theft, or delayed delivery, usually with per-item caps and special limits for valuables.
Emergency assistance is a service, not an automatic promise to pay. A 24-hour assistance team can coordinate care or transportation, but eligibility still depends on the certificate and the facts of the loss.

Start with the risks you actually have
Add up every prepaid expense you would lose if you canceled, including separately booked airfare, hotels, transfers, tours, and parking. Then check whether the plan insures those purchases or only the cruise fare sold by the line.
Next, call your health insurer and ask about emergency care outside the United States, out-of-network rules, direct payment, and medical transport. The CDC warns that travelers may have to pay providers up front and seek reimbursement later, so a card limit and an emergency cash plan still matter.
Finally, judge the itinerary. A short sailing near major hospitals and an expedition itinerary with long stretches far from advanced care present very different evacuation risks even when their cruise fares are similar.
Medical evacuation is about more than the dollar limit
The CDC estimates that a medical evacuation can cost about $25,000 within North America and more than $250,000 from a remote location. That range is a reason to compare limits carefully, not a guarantee that a particular evacuation will cost or be covered for any stated amount.
The insurer or assistance company generally decides whether an evacuation is medically necessary and where you go. Check whether the wording promises only the nearest appropriate facility, permits transport to a hospital of choice, or includes transport home after stabilization.
Also look for preauthorization rules, a physician-backed 24-hour assistance center, direct-payment arrangements, and repatriation benefits. If your itinerary includes diving, ice landings, snowmobiling, or another higher-risk activity, confirm in writing that the activity is not excluded.
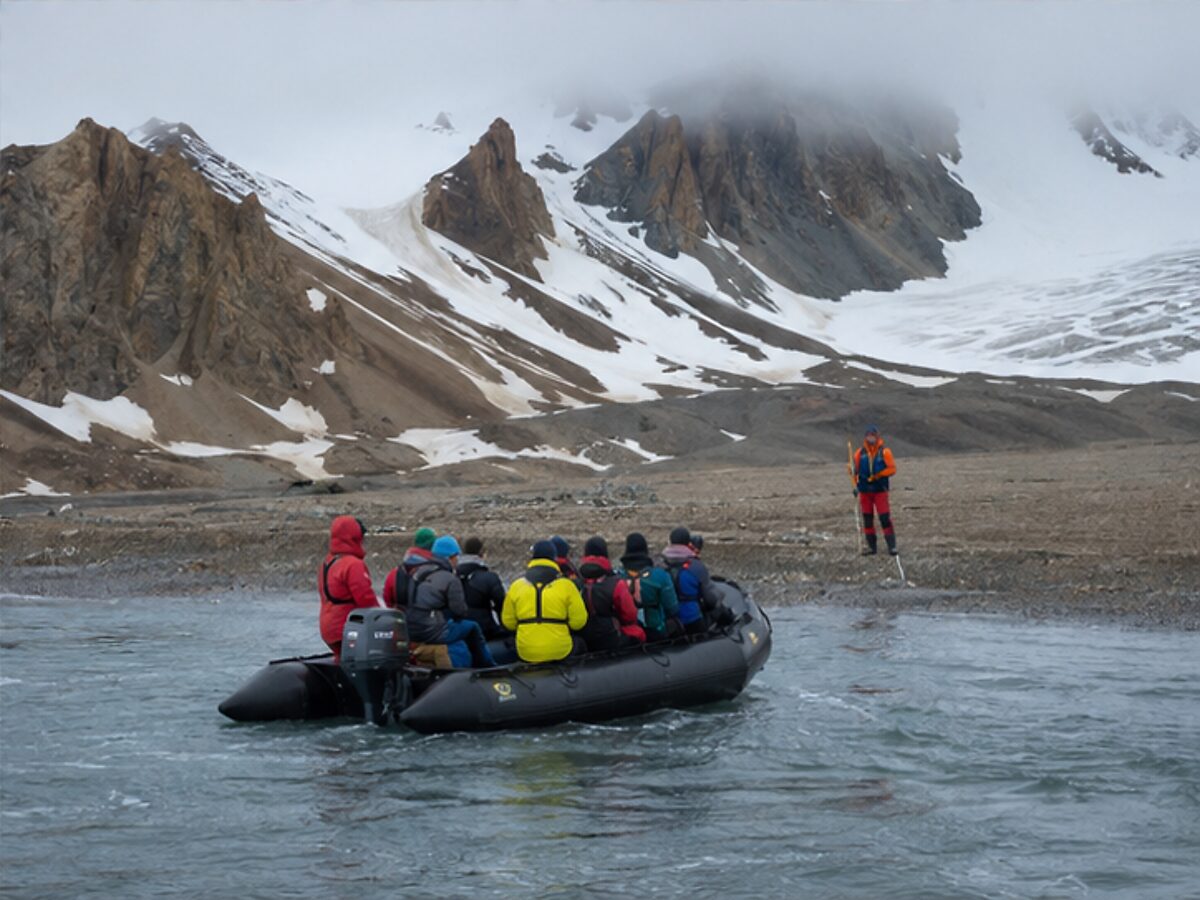
Remote sailings deserve a serious limit check. A North Pole cruise or Antarctica fly-cruise can also carry an operator-specific minimum insurance requirement, so compare that requirement with the exact policy wording before final payment.
What happens when you need care on a cruise
Ship medical care and shoreside care may be billed differently, and the travel insurer may not pay the provider directly. Keep itemized bills, medical notes, proof of payment, and any written instructions from the ship or assistance company.
Call the plan’s emergency assistance number as soon as it is reasonably safe, especially before arranging expensive transportation. Preauthorization can matter, although an immediate emergency may be handled differently under the certificate.
If you are deciding how much medical coverage to buy, review how cruise ship medical-center charges work and then compare those potential expenses with your health plan. A travel medical benefit can be primary or secondary, and that distinction changes which insurer you claim with first.
Medicare, Medicaid, and private health insurance
The U.S. Department of State cruise guidance recommends medical and evacuation coverage and warns that Medicare and Medicaid do not cover medical costs abroad. Medicare itself describes a few limited exceptions, so the precise answer is more nuanced than a blanket no.
Medicare says Original Medicare usually does not cover care outside the United States. Part B may cover medically necessary shipboard services when the doctor is legally allowed to provide them and the ship is in a U.S. port or no more than six hours from one, and rare foreign-hospital exceptions may also apply.
Some Medigap policies include limited foreign emergency benefits, while Medicare Advantage and private plans set their own rules. Ask your plan about the countries on your itinerary, the ship, emergency versus routine care, deductibles, networks, and reimbursement paperwork.
Do not assume your domestic plan includes evacuation to the United States. Medical treatment and medical transport are separate risks, so verify both.
Buy soon after the first trip payment
Shop promptly after your first trip payment rather than waiting for final payment. Time-sensitive options such as a pre-existing-condition exclusion waiver or cancel-for-any-reason coverage may require purchase within a plan-specific window.
The window, look-back period, medical-stability test, and requirement to insure trip costs all vary. If a pre-existing condition could affect you, a traveling companion, or a non-traveling family member, compare the definitions in the certificate before buying.
Add later nonrefundable costs to the policy within the deadline the insurer gives you. That can include airfare, pre-cruise hotels, and tours, and failing to update the insured amount can affect a claim or waiver eligibility.
Read the review or free-look provision as soon as the policy arrives. Refund rights and deadlines vary by plan and state, and they may end after departure or after a claim.
It helps to understand cruise deposits and final-payment dates before you start comparing policies. The first-trip-payment date, not the cruise line’s final-payment date, is often the important clock.
Pre-existing conditions are defined by the policy
Many plans exclude losses connected to a condition that falls within a stated look-back period unless the traveler meets every requirement for a waiver. A diagnosis alone may not be the only test because treatment, medication changes, symptoms, or a recommendation for care can also matter under some definitions.
Do not rely on a generic window such as 14, 60, or 120 days from another product. Check your certificate for who must be medically able to travel, whose health is considered, the look-back period, the purchase deadline, and whether all eligible trip costs must be insured.
Pregnancy deserves the same careful reading. Normal pregnancy may be excluded while an unforeseen complication may be treated differently, and cruise-line boarding restrictions such as the common 24-week pregnancy cutoff are separate from insurance coverage.

Cruise-line protection is often part waiver, part insurance
A cruise line’s protection package may combine a cancellation penalty waiver supplied by the cruise line with insurance underwritten by a separate company. The waiver is not insurance, and its cancel-for-other-reasons benefit may come as a future cruise credit with restrictions rather than cash.
Royal Caribbean’s current program summary labels its cancellation feature as non-insurance. It advertises reimbursement for specified reasons and a 90% future cruise credit for other reasons, while the insurance section advertises up to $100,000 in medical benefits and $500,000 for evacuation and repatriation.
Carnival’s current program summary similarly describes a non-insurance cancellation fee waiver with a 75% future cruise credit for other reasons. Its insurance summary advertises up to $20,000 for medical expenses and $50,000 for emergency evacuation and repatriation.
Those numbers are useful comparison points, but both companies warn that availability and terms vary by state or jurisdiction. Read the certificate and waiver terms offered for your booking because a marketing page is not the contract.
Cruise-line plan, independent plan, or credit card
A cruise-line plan is convenient and may offer a generous future-credit waiver, but it may insure only arrangements bought through the line. An independent comprehensive policy can make it easier to insure the cruise, independent flights, hotels, and tours together, although its exclusions and claims rules still control.
Credit-card benefits can be valuable for eligible purchases charged to that card, but limits, covered reasons, family definitions, and payment requirements vary. The CDC cautions that card benefits require formal claims and do not guarantee reimbursement, so review the benefits guide instead of treating the card as automatic protection.
An annual travel plan can suit frequent travelers, but check per-trip limits, maximum trip length, and whether cancellation coverage is included. Do not assume annual medical or evacuation coverage protects the full price of every cruise.
Cancellation, interruption, and cancel for any reason
Standard cancellation and interruption benefits cover only reasons named in the policy. Common examples can include a qualifying illness or injury, death of a covered family member, certain severe-weather effects, or a home becoming uninhabitable, but definitions and proof requirements vary.
Cancel for any reason, often shortened to CFAR, is different. It usually requires an early purchase, insurance of the required trip costs, and cancellation before a stated deadline, and it commonly reimburses only a percentage of eligible loss.
A cruise-line cancellation waiver is also different from CFAR insurance. It may return a future cruise credit rather than cash and may have redemption deadlines, exclusions, or booking restrictions.
Trip interruption begins after departure and is not simply late cancellation. Check eligible return transportation, unused trip-cost limits, single-supplement charges, and whether the assistance company must approve arrangements.
Weather, missed ports, delays, and missed sailings
A storm warning or itinerary change alone may not trigger a standard cancellation benefit. A named storm or another event that was already known when you bought the policy may also be treated as foreseeable, but the exact cutoff and exclusion language come from the certificate.
Cruise lines can reroute or omit a port without canceling the sailing. Standard trip cancellation usually does not pay simply because the itinerary changed, although some products offer a specific missed-port or cruise-disablement benefit with their own trigger.
See the ports most likely to be missed or canceled if one call is the centerpiece of your trip. Then check whether your policy names missed ports, shore excursions, or change-in-itinerary benefits rather than assuming they are included.
Travel delay and missed-connection benefits can have minimum waiting periods, covered-cause lists, daily caps, and receipt requirements. Arriving late because you left too little time may not be covered, so follow the line’s deadline and use this guide to return to the ship on time.
Exclusions worth reading before you buy
Start with pre-existing conditions, foreseeable events, intoxication, unlawful acts, and self-inflicted injury. Then check pregnancy, mental-health conditions, epidemics, war or civil unrest, government travel advisories, and provider insolvency because plans handle these differently.
Adventure and expedition exclusions deserve their own pass. Scuba diving, climbing, racing, high-altitude activity, and operating certain vehicles may require an upgrade or may remain excluded.
Baggage coverage often has low per-item limits and special rules for jewelry, electronics, cash, medical devices, and unattended property. Airline or cruise-line reimbursement may be primary, so keep their written loss report and settlement.
Supplier default and financial insolvency are not interchangeable terms. If that risk matters, check eligible-supplier rules, purchase timing, and whether the company selling the policy is excluded from the benefit.
A practical buying checklist
- List the trip costs: separate refundable amounts from money you would actually lose.
- Call your health plan: ask about shipboard care, every foreign destination, emergency treatment, and evacuation.
- Compare the certificates: focus on definitions, limits, deductibles, exclusions, and coordination of benefits.
- Check timing: note the first-payment date and every deadline for waivers, CFAR, and adding trip costs.
- Match the itinerary: account for remote ports, expedition activities, weather season, and operator requirements.
- Save the assistance details: put the phone number and policy number in your phone and share them with a companion.
- Document a loss: keep receipts, carrier notices, medical records, police reports, and proof of payment.
Price matters, but a cheap plan with the wrong definition is not a bargain. Compare plans using the same insured trip cost and traveler information, then read the actual certificate before the review period ends.
When self-insuring can make sense
You may reasonably self-insure a small, nonrefundable trip cost if losing it would not disrupt your finances. That decision does not answer the separate question of whether you can absorb foreign medical care or a medically necessary evacuation.
Remote itineraries, older travelers, chronic conditions, expensive nonrefundable bookings, and separately booked air or tours all deserve a closer look. The right answer comes from your risk and the contract, not from a blanket rule that every cruise needs the same plan.

Quick answers
Does health insurance work on a cruise ship?
Your domestic plan may provide limited emergency or out-of-network benefits, but rules vary, providers may require payment up front, and you should ask the insurer about shipboard care, foreign ports, reimbursement, and medical transport.
Does Medicare ever cover care on a ship?
Original Medicare usually does not cover care outside the United States, but Part B may cover qualifying shipboard services in a U.S. port or within six hours of one, Medicare lists a few other rare exceptions, and some Medigap policies offer limited foreign emergency coverage.
How much can a medical evacuation cost?
The CDC estimates about $25,000 within North America and more than $250,000 from remote locations, while actual cost and coverage depend on the circumstances and the policy.
Can I buy coverage after a hurricane is named?
You can still buy a policy, but a loss tied to an already known storm may be excluded as foreseeable, so read its effective-date and known-event language.
Is the cruise line’s plan enough?
It can be, but compare its medical and evacuation limits, covered trip components, state-specific certificate, and future-credit rules with an independent policy.
Will insurance pay when the ship skips a port?
Not automatically, so look for a specific missed-port or itinerary-change benefit and read its trigger, exclusions, and payment limit.
The last word
Cruise insurance is not one benefit, and no guide can guarantee how a claim will be decided. Protect the losses that would hurt you, pay special attention to medical transport on remote routes, and let the certificate settle every close call.
Where you sail can matter as much as what you paid. Compare the policy early, keep the assistance number handy, and leave enough room in your budget for expenses you may have to pay before reimbursement.
How this guide was researched: Coverage categories, payment cautions, and evacuation costs were checked against the CDC Yellow Book, while cruise-specific safety guidance was checked against the U.S. Department of State. Medicare rules were checked against Medicare.gov, and current cruise-line plan examples were checked against Carnival and Royal Caribbean.
Terms vary by insurer, plan, booking, and state, and the certificate or waiver supplied for your purchase controls. Details were reviewed in September 2026; see our Editorial Policy.
More on this topic: browse every guide on choosing a cruise.